If you want to start a startup, the short answer is a sequence: find a problem people already pay to solve, describe exactly who has it, test whether they'll pay you, build the smallest product that fixes it, and launch to a small group. Then repeat until customers start coming back on their own. Each step reduces the risk of the next one, and skipping steps is the most common reason new companies stall.
Most first-time founders start with an idea and a long list of urgent-feeling tasks: code, logo, registration, a pitch deck. Months can pass on that list without learning whether anyone wants the product. Knowing how to start a startup in the right order prevents that.
Start With a Problem, Not an Idea
The first of the steps to start a startup is finding a problem that hurts. Ideas are cheap and easy to fall in love with. Problems are harder to find, but they come with a market attached: people who have them already spend time or money trying to make them go away.
Ask potential customers how they deal with the issue today. Spreadsheets, freelancers, clunky paid tools, or weekly workarounds mean the problem is real. If they shrug and call it "a bit annoying," move on.
Talk to strangers who fit your target customer, since friends and family will be kind. Ask about recent experiences with the problem, what it cost them, and what they tried. Hold back your pitch, because people politely agree with whatever you show them.
Expect your view of the problem to shift. Troy Mott, founder of MyFiveRavens, set out with a narrow goal: sell one book and build a website. As he worked through questions about his real audience, pricing, and competitors, he ended up building a broader platform for his work instead of a single product page. Understanding how to start a business that lasts often begins with this rethink, and it's far cheaper to have it before you build than after.
The Core Steps to Launch
Here's how to start a startup in practical order. Problem first, then customer, then validation, then a minimal product, then launch.
Once the problem is clear, define the person who has it. "Small businesses" is too broad to act on. "Owners of independent bakeries with two to five staff who handle supplier orders by phone" is someone you can find, call, and understand. Our glossary entry on the ideal customer profile explains how to describe this person precisely.
Next, test whether they'll pay. Pre-orders, deposits, signed letters of intent, or paid pilots are the strongest proof. Email signups are useful but weaker. Only after that do you build a minimum viable product: the smallest version that solves the core problem for this one customer group.
Use this lightweight startup checklist for the early stages:
- Pick a problem. Write down three problems you could solve and pick the one with the clearest evidence of pain.
- Interview. Talk to at least 20 people who have that problem.
- Landing page. Build a one-page site describing your solution and price.
- Measure interest. Collect pre-orders, deposits, or at least email signups.
- Build the core. Build only the one feature that removes the main pain.
Do these in order. A big part of how to start a startup is deciding what to ignore. A polished logo, an office, a complex legal setup, and a detailed five-year forecast can all wait until money is changing hands. Register the company when you're about to take payments or sign contracts.
Validate, then sell, then build. Founders who code in private for six months often launch to silence. Launch itself is modest: invite the first 10 or 20 users and watch how they use the product.
Starting With Little or No Money
Learning how to start a startup with no money is mostly about where you spend effort. The most important early work, finding customers and learning what they need, costs time rather than cash.
Before spending anything, try to sell the concept. Post in communities where your customers gather, send short personal emails, offer a pre-order at a discount. In 2026, no-code builders, AI assistants, and free software tiers make the first version cheaper than ever. Another useful rule for how to start a business on a small budget is to pay only for things that help you prove demand.
A quick split of where money goes early on:
- Usually needs some cash: a domain, basic hosting, a few software subscriptions, small payment processing fees.
- Needs time only: customer interviews, outreach, landing page copy, collecting pre-orders, manual delivery of your service to the first users.
- Can wait: paid ads, branded merchandise, premium domains, an office, agencies.
Track spending from day one. The free burn rate and runway calculator shows the exact date your cash runs out at the current pace.
Bootstrapping keeps you in full control. Raise money once you know what works and need speed, since investor cash spent figuring out what to build usually disappears fast. If you're exploring how to start a startup with no money, keeping your job during validation is a reasonable choice and not a sign of weak commitment.
The First 90 Days
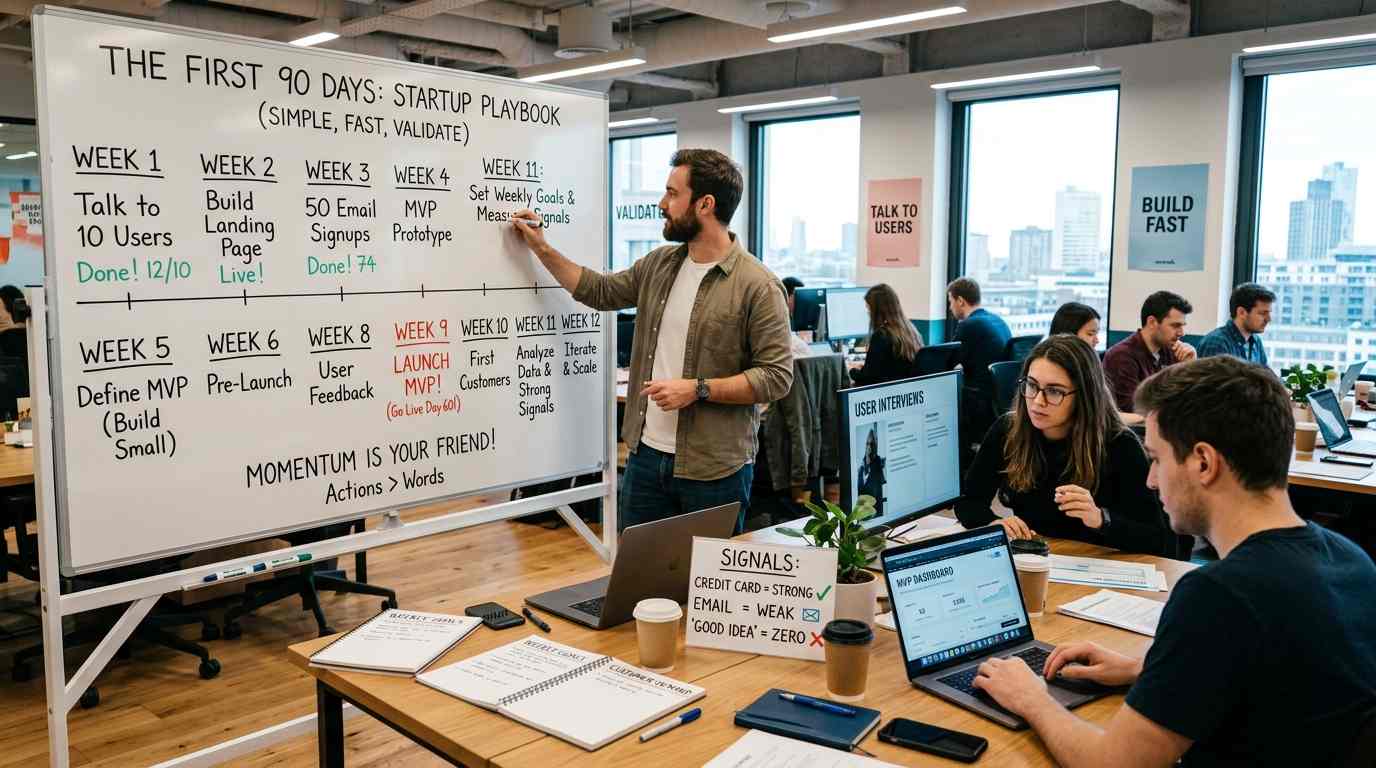
The first three months decide whether you have something worth continuing. Treat them as a startup playbook with one goal: get a small product into the hands of paying or committed users.
Set weekly targets instead of long-term plans. A simple outline:
- Weeks 1-3: interview 20 or more potential customers and write down the patterns you hear.
- Weeks 4-6: launch a landing page with a clear offer and price, then drive targeted traffic to it through outreach and communities.
- Weeks 7-10: build the smallest product that delivers the core result, even if parts of it are manual behind the scenes.
- Weeks 11-13: onboard your first users, watch how they use it, and fix the biggest friction points.
Measure behavior, because opinions are unreliable. A credit card number or signed agreement is a strong signal. A sign-up with an email is a moderate one. "Sounds like a great idea" tells you almost nothing.
By day 90, you should have a live product with rough edges, used by real people. Tight weekly deadlines matter more than polish, because momentum carries founders through the uncertain early months of how to start a startup.
Common First-Time Founder Mistakes
Knowing how to start a startup, or how to start a business of any kind, also means recognizing the traps that catch most first-timers.
Building too early tops the list. Code feels productive and safe; customer calls feel awkward. Many founders hide in the product for months and only then learn nobody needed it.
Lack of focus comes second. Ten half-built features help nobody. A good startup playbook forces you to make one thing work for one group of people before you add anything else.
Ignoring feedback is costly too. If several users find onboarding confusing, fix it. Raising too early is the last trap. Investor money before you understand your customer mostly speeds up spending.
Before each new stage, ask yourself an honest question: does this task help a customer, or does it just make me feel busy? That one check catches most of the mistakes above.
Frequently Asked Questions
How do you start a startup? Find a problem people already spend time or money on, define who has it, test whether they'll pay, build a minimal product, and launch it to a small group. That sequence is the core of how to start a startup in 2026.
What are the first steps to start a startup? The first steps to start a startup are identifying a painful problem, clearly defining your ideal customer, and validating demand through interviews and pre-orders. A short startup checklist helps you stay on track.
How do you start a startup with no money? Validate cheaply. Use free tools, pre-sell before building, and keep your job while testing demand. Spend only on things that prove people want the product.
What should you do in the first 90 days? Follow a simple startup checklist: talk to at least 20 potential customers, test an offer on a landing page, build a minimal product, and get it into real users' hands. Measure what people do, then decide what to build next.
Start With a Map, With solvee
Most first-time founders work hard, just on the wrong things in the wrong order. Reading another article on how to start a startup helps less than a system that knows your business. solvee is a personalized AI accelerator that guides founders from first idea to product-market fit.
You start by describing your business, or simply entering your website. solvee scores your customer, value proposition, positioning and offer, then names the three gaps to fix first. A guided program then walks you through each of these, tested against real customer conversations. Each morning it picks the few tasks that move your business forward and explains why they come first.
Its advisor learns your business and challenges weak assumptions. It works like a mentor available every day, with no equity involved. For anyone figuring out how to start a business without a network of experienced advisors, that daily guidance fills a real gap.
Ready to build in the right order? Get free access to solvee and run the free analysis of your business. It takes about a minute, and you'll know what to work on tomorrow morning.